Inheriting a Wine Cellar: Care, Appraisal, and Sale
Protect, inventory, insure, and appraise an inherited wine cellar, then sell, donate, or divide it within federal, state, and IRS rules.
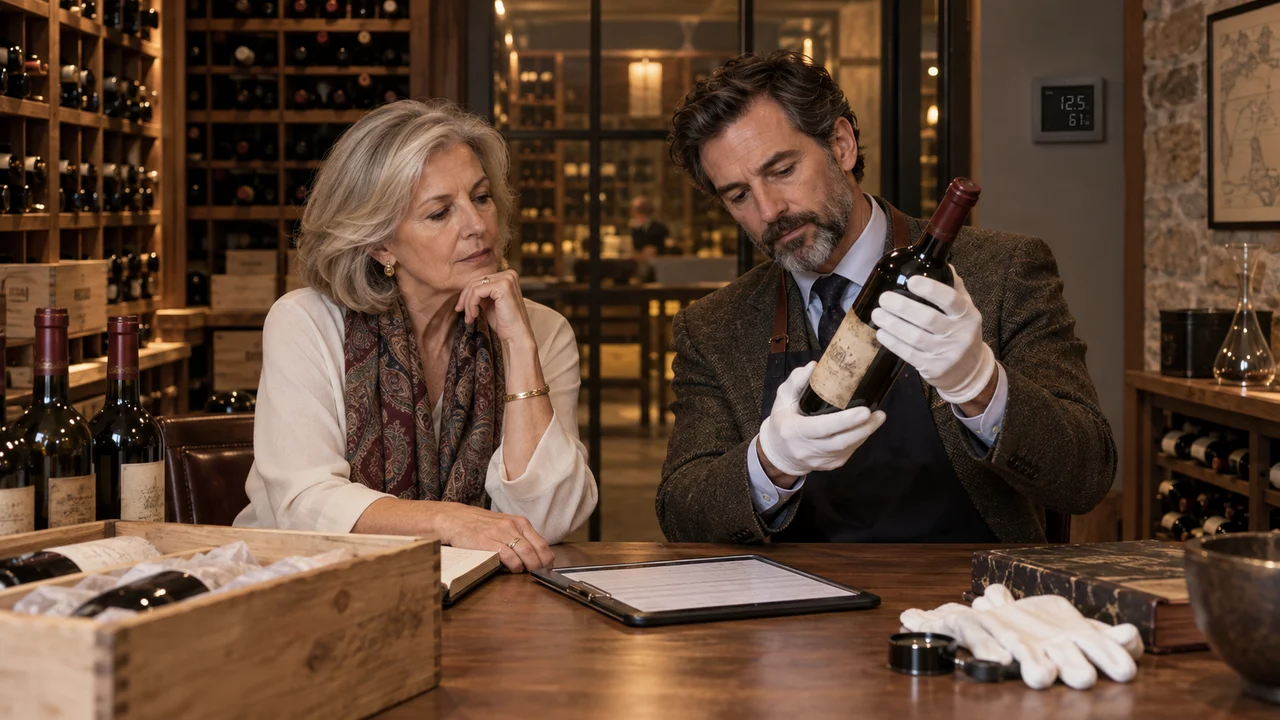
A wine cellar is the one collection in the house that can spoil while the estate is still being settled. Paintings wait patiently for an appraiser; a rack of mature Burgundy does not forgive a failed compressor in August. It is also a collection you cannot simply sell and ship like the dining chairs: federal rules distinguish a personal liquidation from being in the alcohol business, while state licensing, consignment, auction, transport, and delivery rules vary.
This guide takes the decisions in the order they arrive: protect, record, insure, and value the wine, then keep, sell, give, or divide it. By the end you should know which steps cannot wait, which specialists to hire, and which routes to a sale or a gift are open to you.
Keep the cellar cool before you do anything else
Confirm that the cooling unit is running, that the electricity and any service contract are paid from estate funds, and that someone besides you knows how to reach the cellar. Heat, and the temperature swings that follow a power cut, do damage no later care can reverse.
A few measures cost little against the stakes:
- a monitor that sends temperature alerts to you and a second person;
- a technician’s inspection of the cooling unit;
- backup power where possible, and a named person who checks the cellar after an outage; and
- a record of who holds keys or codes, especially if the house will stand empty.
If the house is to be sold or closed, professional storage may be safer than an unattended cellar. Move the wine once, in cool weather, with a specialist carrier and transit insurance.
Build an inventory a buyer would trust
The Treasury regulation on valuing household and personal effects calls a room-by-room itemization desirable, each article named and valued, although articles in one room worth no more than $100 each may be grouped. Count everyday bottles together; list anything of consequence alone.
For each wine, record producer, name, vintage, bottle size, quantity, and location. Note condition as a specialist would: fill level, label, capsule, and whether bottles remain in their original wooden case. Photograph racks and notable bottles.
Then gather the paper: purchase invoices, the cellar book, storage statements, and temperature logs, the provenance record a serious buyer will ask for. Look for wine outside the house, too: in professional storage, held by a merchant, or paid for before release but not yet delivered.
The value of a great bottle lies partly in what can be proved about where it has been.
First establish who owns the cellar. Some or all of it may already be yours, through joint ownership or your state’s marital or community property law; ask the estate’s lawyer. Whatever belongs to the estate or a trust stays there until it is distributed, and a bottle opened at a family dinner comes out of someone’s inheritance. If the will leaves the cellar to a particular person, keep a note of what is drunk.
Insure at replacement value, and keep that number separate
Tell the insurer about the death and confirm who is now the named insured. Then ask whether the policy limits or excludes wine, and whether it covers spoilage from a power failure or equipment breakdown, wine held off the premises, and wine in transit. Where the answers fall short, a scheduled policy at appraised values is the usual remedy; our guide to insuring a high-value household covers the specialist market.
Keep two figures apart. IRS Publication 561 makes the point with jewelry: an appraisal obtained for insurance reflects replacement cost, not the price a willing buyer would pay a willing seller. The estate needs the second figure.
The estate’s value: a sworn, specialist appraisal
For federal estate tax, the regulation values household and personal effects at the price a willing buyer would pay a willing seller, neither compelled to act and both reasonably informed. If an estate tax return is required and the effects include articles of “marked artistic or intrinsic value” worth more than $3,000 in total, an expert’s appraisal under oath must be filed with the return, accompanied by the executor’s statement, under penalties of perjury, on the list’s completeness and the appraiser’s qualifications and independence. Wine is not among the regulation’s examples, which include silverware, books, and coin collections, so the executor and return preparer should decide whether the cellar falls within that rule; a serious cellar needs a supportable specialist valuation in any event.
The regulation asks for appraisers competent in the particular class of property, which argues for a wine specialist. Publication 561’s test for appraisers of donated property is a sound benchmark: a recognized designation, or relevant coursework and at least two years of experience with that type of property; regular paid appraisal work; and no fee based on a percentage of value. An auction house’s estimate, offered in hope of a consignment, is not an independent appraisal.
The value the estate settles on can follow you for years, which is why our guide to valuing assets at the date of death treats the appraisal file as a permanent record.
Why wine is sold through licensed hands
The Alcohol and Tobacco Tax and Trade Bureau (TTB) administers the Federal Alcohol Administration Act, which imposes permit requirements on people engaged in specified alcohol businesses, including wholesaling. Federal dealer rules can also presume wholesale activity when a dealer sells 20 wine gallons or more to another dealer at one time. Neither point supplies a nationwide permission for an executor’s one-time sale. TTB notes that each state regulates alcohol sales and distribution within its borders, and state rules vary widely and may be stricter than federal law.
Do not infer from the federal “engaged in business” standard that a private sale is lawful. Before advertising, accepting money, transferring a bottle, or shipping it, ask the state alcohol authority where the wine is located what rule applies to an estate or private collection and whether a license, auction permit, or licensed intermediary is required. Our guide to selling the contents of a house sets alcohol aside for this reason. The customary routes are an auction house licensed to sell wine on consignment, or a licensed merchant, where state law lets a merchant buy from or sell for a private cellar. Ask the intermediary to identify in writing the license and state rule supporting the transaction. TTB publishes a directory of state alcohol authorities.
Compare written proposals on commission and charges, timing, the state and license under which the wine will be sold, and what happens to unsold lots. Confirm who may sign: the executor, the trustee, or you. If an early sale departs sharply from the appraisal, tell the appraiser and preparer before the estate’s figures are final.
Moving wine across state lines
Two federal rules frame every shipment. The Postal Service treats intoxicating liquors as nonmailable, expressly including those obtained as a collector’s item, under 18 U.S.C. § 1716. And the Webb-Kenyon Act, which TTB administers, prohibits shipping alcohol beverages into a state in violation of that state’s laws.
The destination’s rules therefore govern, whether the wine is bound for an auction house or a daughter’s home. Let a licensed buyer or auction house arrange transport, or confirm the receiving state’s rules with its alcohol authority before a case is packed.
Giving wine to a charity
Wine is tangible personal property, which Publication 526 defines as property other than land or buildings that can be seen or touched. For appreciated capital gain property the deduction is generally fair market value, but not when the charity puts such property to a use unrelated to its exempt purpose. The deduction is then reduced by the long-term gain you would have had on a sale, which generally leaves your basis. The IRS’s example: a painting a school displays for its art students is a related use; a painting the school sells is not. By that reasoning, wine given for a gala auction is likely an unrelated use.
For tangible personal property with a claimed value above $5,000, two further rules can matter. If the charity disposes of it in the year of the gift without the required exempt-use certification, the deduction is reduced under the unrelated-use rule. If it disposes of it after that year but within three years, recapture generally applies only when your claimed deduction exceeded basis and the charity does not certify substantial related use or that the intended use became impossible. Get the charity’s intended use in writing, and ask how it will sell or serve alcohol lawfully; the charity may also have to report a disposition on Form 8282.
A deduction of more than $5,000 for an item or group of similar items requires a qualified appraisal and Section B of Form 8283; aggregate similar wine gifts to every charity during the tax year when testing the threshold. The charity’s Form 8283 signature acknowledges receipt, not the claimed value, and a separate contemporaneous written acknowledgment is generally required for a contribution of $250 or more. The qualified appraisal must be signed and dated no earlier than 60 days before the gift and no later than the return’s due date, including extensions; if it is dated on or after the gift, its valuation effective date must be the gift date. You must receive it by that return deadline, and its fee is not deductible as a charitable contribution. For wine you inherited, you are treated as having held it longer than one year, and its basis is generally its fair market value at the date of death, so the unrelated-use reduction usually reaches only any rise in value since then; a share that was already yours may carry a different basis. Ask your preparer what your basis is, and so what that rule would cost, before you promise the cases to anyone.
Publication 526 is the 2025 edition, and two changes apply beginning in 2026. IRS Publication 505 says an itemizer may deduct charitable contributions only to the extent the year’s aggregate exceeds 0.5 percent of adjusted gross income; the amount absorbed by that floor is not deductible in 2026. A separate overall limit reduces the tax benefit of itemized deductions for taxpayers in the 37 percent bracket. Ask your preparer to model both limits, the percentage ceiling for the particular gift and charity, and any carryover before you choose the year of the donation.
Dividing a cellar among heirs
Start with the will or trust: a specific gift of “my wine” goes to the person named, while a cellar in the residue is shared like other residuary property. Value the bottles from the estate appraisal before anyone chooses, so shares can be equalized with cash or other assets.
Write the method down. Some families take turns in an order drawn by lot; others have the appraiser form lots of comparable value. Ask before breaking up original cases, which can affect what bottles later fetch. An heir who prefers money can have that share sold through a licensed channel, bearing its own commission. Record every bottle released on a signed receipt; our guide to distributing personal possessions covers selection methods and receipts.
Questions to settle before a bottle leaves the house
- Is the cooling system monitored, serviced, and backed up?
- Does a photographed inventory record each notable bottle’s condition and location?
- Have you found wine in storage, at a merchant, or bought before release?
- Has the insurer confirmed cover for spoilage, off-site storage, and transit?
- Has an independent wine specialist on a flat or hourly fee appraised the cellar?
- If an estate tax return will be filed, is the appraisal sworn?
- Who may sell, and which licensed auction house or merchant will?
- Have the receiving state’s rules been confirmed for each shipment?
- For a gift, is the charity’s intended use in writing?
- For heirs, is the selection method written, with a signed receipt for each share?
This article provides general U.S. educational information and is not legal, tax, appraisal, or insurance advice. Confirm current rules with your state’s alcohol authority, the IRS, and a qualified professional who knows your facts.
Primary sources
- Alcohol and Tobacco Tax and Trade Bureau: Alcohol Beverage Authorities in United States, Canada, and Puerto Rico
- Alcohol and Tobacco Tax and Trade Bureau: Statutory Authorities and Responsibilities
- Alcohol and Tobacco Tax and Trade Bureau: Liquor Laws and Regulations for Retail Dealers
- U.S. Postal Service: Publication 52, Section 424, Nonmailable Intoxicating Liquors
- Electronic Code of Federal Regulations: 26 CFR § 20.2031-6, Valuation of household and personal effects
- Internal Revenue Service: Publication 561 (12/2025), Determining the Value of Donated Property
- Internal Revenue Service: Publication 526 (2025), Charitable Contributions
- Internal Revenue Service: Publication 505 (2026), Tax Withholding and Estimated Tax
- Internal Revenue Service: 2026 tax inflation adjustments
This article provides general education, not individualized legal, tax, investment, insurance, or benefits advice. Rules and deadlines change; verify the current requirement with the agency and a qualified professional.
More from Private Wealth
The desk →
Private Wealth
Before Buying a Private Fund: A Due-Diligence File
Review a private fund before subscribing: strategy, manager, fees, conflicts, liquidity, capital calls, valuation, tax reporting, side letters, and estate transfer.

Private Wealth
Charitable Lead Trusts: Charity First, Family Later
Learn how charitable lead annuity and unitrust arrangements divide payments between charity and family, and examine gift, income-tax, investment, filing, and governance tradeoffs.

Private Wealth
Family Limited Partnerships: Control, Value, and Risk
Understand what a family limited partnership can organize, why real operation matters, and how to document funding, gifts, valuation, tax reporting, and succession.