Buying Art: Provenance, Condition, and Sale Terms
How galleries, auctions, dealers, and advisers are paid, what conditions of sale promise, and the provenance, condition, tax, and record checks to make first.
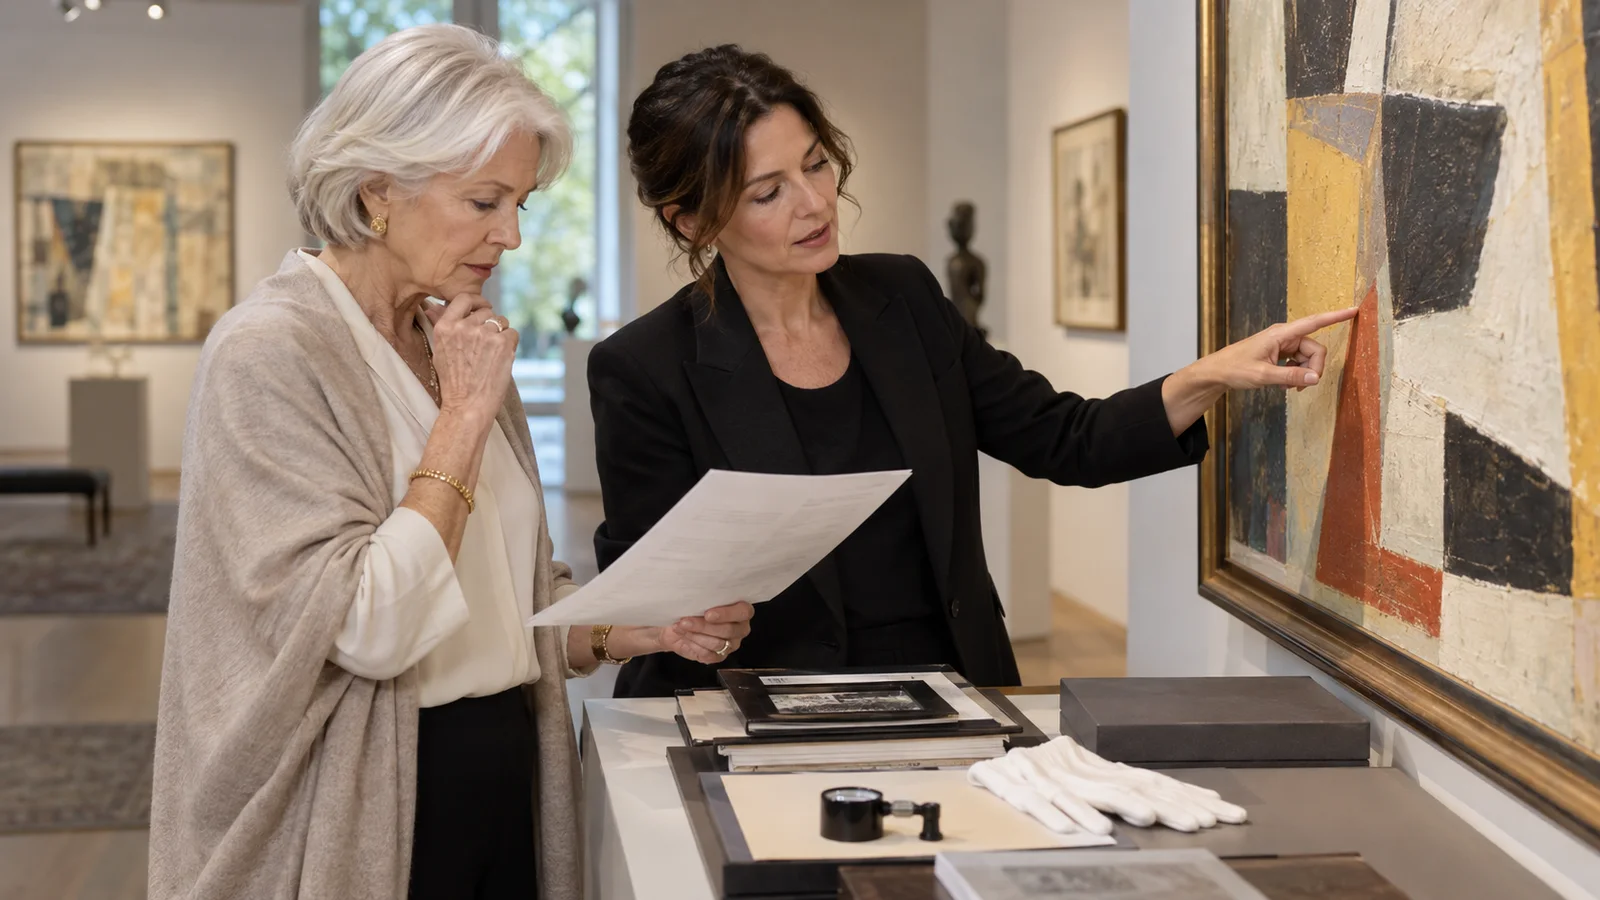
A work of art is sold twice: once to your eye, and once in the paperwork that decides what you actually own. The first takes a moment. The second, written in conditions of sale, condition reports and provenance files, governs what you can do if the attribution is doubted, the canvas proves weaker than it looked, a former owner comes forward, or you decide, years from now, to sell.
Perhaps you chose together and your spouse handled the terms. The decisions are now yours. Before bidding or wiring funds, identify whom each intermediary represents, calculate the all-in price, read the warranty and risk-transfer clauses, and make the purchase conditional on any provenance or condition work still outstanding.
Know whom each seller works for, and how each is paid
A gallery usually sells for the artists it represents and shares the price with them. A dealer may own the work outright and sell at a margin, or hold it on consignment; ask which, because it changes who stands behind the title. An auction house generally acts for the seller, who pays it a commission, while you pay the hammer price plus a buyer’s premium and any tax. An art adviser works, in principle, for you, paid by flat fee, hourly rate, retainer or a percentage of what you buy.
Ask the adviser, in writing, whether anything is received from the other side of the transaction. A percentage fee rewards a larger purchase; a payment from a seller rewards a particular one. Either is a reason to see the seller’s own invoice.
Read the conditions of sale before the catalogue
At auction, the conditions of sale are the contract. Under Article 2 of the Uniform Commercial Code, a model law that states enact with their own variations, an auction sale is complete at the fall of the hammer, so read before you register to bid. Look for four things:
- The buyer’s premium. It is added to the hammer price at the rate the conditions set. Set your limit on the total, tax included.
- “As is” language. The Code lets a seller exclude implied warranties with expressions such as “as is” or “with all faults.” If you examined the work, or declined to, there is no implied warranty for defects that examination ought to have revealed.
- The authenticity warranty. Where one is offered, read whom it protects, which words it covers, how long it lasts and whether the only remedy is a refund.
- The glossary. Phrases such as “attributed to” carry the meanings the glossary gives them, and the Code says a statement that is merely the seller’s opinion does not create a warranty.
With a gallery or dealer, ask for the attribution, date and provenance on the invoice itself. Under the Code, a description that becomes part of the basis of the bargain creates an express warranty.
Commission your own opinion on condition
A condition report from the seller is written by the seller’s side, and one offered as opinion gives you little to rely on. For a work of consequence, have a conservator of your own examine it before the sale, or make a private purchase conditional on that examination.
The American Institute for Conservation lists Professional Members whose work has been reviewed by their peers; anyone may join the institute, but only Professional Members have passed that review. The institute says a conservator should examine an object before proposing treatment, give you a written report describing the proposed treatment, expected results and estimated cost, and finish with a report listing materials and procedures. Before purchase, the same examination tells you what you are buying: old repairs, overpaint, instability and the likely cost of care.
Treat provenance as a chain of title
Under the Code, a seller warrants that the title conveyed is good, although specific language can exclude that warranty. More fundamentally, a buyer acquires only the title her seller had or had power to transfer. Good faith helps only in narrower cases, such as where the seller’s title was voidable rather than absent, or where the owner had entrusted the work to a dealer who then sold it in the ordinary course of business. A work stolen somewhere in its history may still belong to someone else, however properly you paid, and state law, including limitation periods, shapes the outcome.
Ask for the ownership history in writing, with gaps identified rather than smoothed over, and for the documents behind it. Search the FBI’s National Stolen Art File, an index of stolen art and cultural property reported to the Bureau by law enforcement agencies here and abroad, and ask which other registries the seller has checked. A clean search is evidence, not a guarantee; a database holds only what someone reported.
Provenance is not the story that travels with a work; it is the evidence that the seller had the right to sell it.
Check the border before you buy abroad
Antiquities and certain traditional objects raise a separate question: whether they may lawfully enter the United States. Under the Convention on Cultural Property Implementation Act, archaeological material means culturally significant objects at least 250 years old, normally discovered by excavation, digging or exploration; ethnological material means products of tribal or nonindustrial societies important to a people’s heritage.
Where such material has been designated by regulation for a particular country, it may not be imported without that country’s certification that the export was lawful, or satisfactory evidence that it left the country before designation or, under conditions the statute sets, at least ten years before entry. Without those papers, customs holds the object in a bonded warehouse at the consignee’s risk and expense, and after 90 days, unless more time is allowed, it becomes subject to seizure and forfeiture. Make any purchase from abroad conditional on export documents, and have a customs broker or lawyer check the current designations first.
Budget for sales and use tax
Sales tax is a state and local matter, and rules vary. A seller shipping across state lines may not collect your state’s tax, but that does not make the purchase tax-free. New York, for one, imposes use tax on taxable items bought elsewhere and brought into the state, generally calculated on the price including shipping and handling. It may allow a credit for sales tax paid to another state, and an individual who owes sales or use tax on a single item costing $25,000 or more, excluding shipping and handling, must also report it on Form IT-135. Ask your preparer how your state treats art bought online or out of state, and whether a second residence changes the answer.
Insure it from the moment it is yours
Find the point in the conditions of sale at which the work is at your risk, and have coverage from then, including transit and time with a framer or conservator. Schedule it at a documented value and revisit that value periodically. Our guide to insuring a high-value household covers scheduling and specialist carriers.
Framing is part of conservation. Glazing, mounts and hardware protect or harm a work for decades, and the institute notes that preventive-care specialists advise on preventing damage. Have the frame, wall and light reviewed before the work goes up.
Keep the file that sets your basis
IRS Publication 551, revised December 2025, says the basis of property you buy is usually its cost, including sales tax and freight: for art, generally the hammer price, premium, tax and shipping. Improvements with a useful life of more than one year increase basis; ask your preparer whether a major conservation treatment qualifies. IRS Topic 409 says net capital gain from collectibles such as art is subject to a maximum 28% rate (not that every collectible gain is automatically taxed at 28%)and losses on personal-use property are not deductible. IRS Topic 559 imposes the 3.8% net investment income tax on the lesser of net investment income or the amount by which modified adjusted gross income exceeds $200,000 for a single or head-of-household filer, or $250,000 for married filing jointly or a qualifying surviving spouse. Whether a work is held for pleasure or investment is worth settling with your preparer before you sell.
Keep the invoice, conditions of sale, condition and treatment reports, provenance, customs papers, appraisals and insurance schedules together. An executor will need the same file, and it lets heirs distribute personal possessions fairly. What happens to art within an estate, including basis at death, is covered in art and collectibles in a wealthy estate.
Questions to ask before you commit
- Whom does each party act for, and how is each paid on this sale?
- What is the total cost, including premium, tax, shipping and transit insurance?
- What does the authenticity warranty cover, for how long, and with what remedy?
- Has my own conservator examined the work, in writing?
- Where are the gaps in the ownership history, and which stolen-art registries were searched?
- If the object comes from abroad, what export documents exist?
- Will the seller collect sales tax, or will I owe use tax at home?
- From what moment is the work at my risk, and is it insured from then?
- Are the attribution, date and provenance written on the invoice?
- Where will the purchase file live, and who else knows?
This article provides general U.S. educational information and is not legal, tax, customs, insurance, or investment advice. Confirm current rules with the relevant agency and a qualified professional who knows your facts.
Primary sources
- Uniform Commercial Code (Legal Information Institute): § 2-316, Exclusion or Modification of Warranties
- Uniform Commercial Code (Legal Information Institute): § 2-312, Warranty of Title
- Uniform Commercial Code (Legal Information Institute): § 2-313, Express Warranties
- Uniform Commercial Code (Legal Information Institute): § 2-328, Sale by Auction
- U.S. Code (Legal Information Institute): 19 U.S.C. § 2606, Import restrictions
- American Institute for Conservation: Hiring a Conservation Professional
- New York State Department of Taxation and Finance: Taxable purchases
- Internal Revenue Service: Publication 551 (12/2025), Basis of Assets
- Internal Revenue Service: Topic No. 409, Capital Gains and Losses
- Internal Revenue Service: Topic No. 559, Net Investment Income Tax
- Federal Bureau of Investigation: National Stolen Art File
This article provides general education, not individualized legal, tax, investment, insurance, or benefits advice. Rules and deadlines change; verify the current requirement with the agency and a qualified professional.
More from Living Well
The desk →
Living Well
Air Travel with Mobility Needs: A Door-to-Door Plan
Plan accessible air travel from curb to hotel, document a wheelchair or scooter, request the right assistance, and know whom to call when service fails.
Living Well
Choosing a Medical Alert System: A Home Test
Choose and test a medical alert system by matching coverage, monitoring, fall detection, response rules, power, privacy, contracts, and daily habits.
Living Well
Emergency Planning When You Live Alone: Support, Power, and Evacuation
Build an emergency plan for one-person households with a support network, medication and power contingencies, evacuation transport, records, and practiced check-ins.